DSCR Basics
How DSCR Loans Work
A DSCR loan is designed for a non-owner-occupied investment property. Instead of beginning with a conventional personal debt-to-income calculation, the review begins with the rental property, its qualifying income, its expected housing expense, and the complete risk profile of the transaction.
What does DSCR mean?
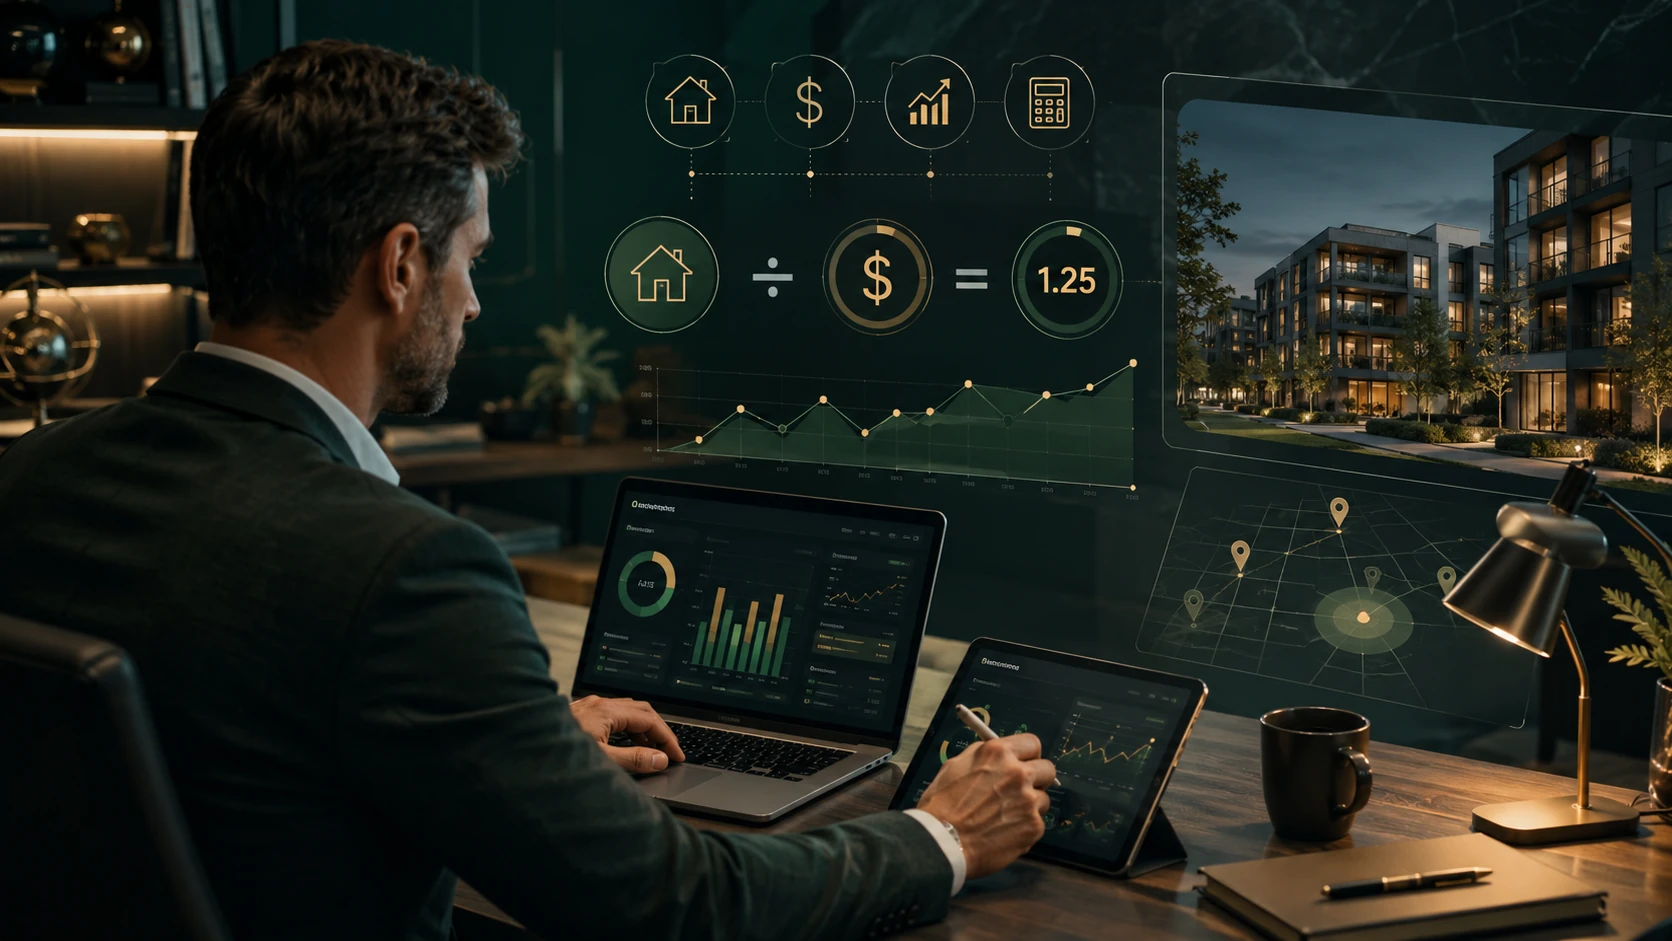
DSCR stands for debt service coverage ratio. In a typical one-to-four-unit rental-property DSCR program, the lender compares qualifying monthly rent with the qualifying monthly housing expense. The exact treatment of rent, taxes, insurance, association dues, and other expenses varies by program.
A simple working formula is: qualifying monthly rent divided by qualifying monthly PITIA or debt service. PITIA generally refers to principal, interest, property taxes, homeowners insurance, and applicable association dues.
Guru note: Example: $5,000 in qualifying monthly rent divided by $4,000 in qualifying monthly PITIA equals an estimated 1.25x DSCR. That example explains the math; it does not promise that a particular lender will approve the loan.
A ratio above, at, or below 1.00x
At 1.00x, the modeled rent equals the modeled debt service. Above 1.00x, the property shows more qualifying rent than modeled housing expense. Below 1.00x, the modeled housing expense exceeds the qualifying rent.
A stronger ratio may support a stronger scenario, but it is not the only factor. Some programs may consider lower ratios with different leverage, credit, reserve, pricing, or property requirements. Other programs may require more coverage. The complete file controls.
How qualifying rent is established
The rent used in the calculation is not always the number shown in an online listing or the investor’s own projection. Depending on the program and property, the lender may review an executed lease, appraisal rent schedule, market-rent analysis, property operating history, or an accepted short-term-rental income method.
Vacancy, lease terms, related-party arrangements, seasonal income, and unsupported rent increases can affect the usable figure. That is why the Guru intake separates the investor’s stated rent from the documentation that will ultimately support it.
What a DSCR lender reviews beyond the ratio
A DSCR loan is not a no-document loan. The lender still evaluates the property, credit profile, requested leverage, reserves, title, entity structure, insurance, loan purpose, appraisal, rent support, and other program-specific requirements.
- Property type, condition, use, and marketability
- Purchase price or current appraised value
- Requested loan amount and resulting loan-to-value ratio
- Credit history and housing-payment history
- Liquidity, reserves, and funds required to close
- Lease, market rent, or approved short-term-rental support
- Entity and vesting documents when an LLC or other approved entity is used
- Seasoning, payoff, and use of proceeds for refinance or cash-out transactions
- State eligibility and business-purpose, non-owner-occupied use
Purchase, rate-term refinance, and cash-out
For a purchase, the file connects the contract price, down payment, requested loan amount, rent, property type, credit, reserves, and closing timeline.
For a rate-term refinance, the review focuses on value, current payoff, new loan amount, property cash flow, seasoning, and the reason for replacing the existing debt.
For cash-out, the lender also reviews the requested proceeds and their business or investment purpose. A free-and-clear property begins with an existing payoff of zero, but value, leverage, rent, seasoning, credit, and complete underwriting still apply.
The DSCR loan process
- Build the initial scenario using property value or purchase price, requested loan amount, rent, and estimated expenses.
- Review the available structure, including leverage, term, amortization, prepayment options, and estimated pricing.
- Complete the application and provide the property, borrower, entity, title, insurance, asset, and transaction documents requested.
- Order and review the appraisal, rent analysis, title, insurance, and other third-party items.
- Clear underwriting conditions and confirm the final loan structure.
- Sign the closing documents and fund after all lender, title, and closing requirements are satisfied.
Common mistakes that slow down a DSCR file
- Using unsupported rent instead of the rent a program can accept
- Leaving taxes, insurance, flood insurance, or HOA dues out of the payment
- Mixing purchase, rate-term, and cash-out numbers in the same scenario
- Treating a free-and-clear property as though it has an existing payoff
- Assuming a good ratio overrides credit, reserves, property, title, or seasoning issues
- Waiting until the end to disclose entity, occupancy, property-condition, or title complications
The bottom line
The fastest DSCR review starts with clean property math and complete deal inputs. Use the calculator to estimate the ratio, then move the actual property into the connected quote flow for a professional review.
About the author
Nicholas M Moss
Managing Partner, NonQM123
Nicholas M Moss is the Managing Partner of NonQM123. He writes about DSCR and Non-QM financing for real estate investors, with a focus on clear deal structure, efficient intake, and business-purpose rental-property lending.
Move the deal forward
Have a rental-property scenario?
Move from general education into a property-specific DSCR review. Start with a property scenario; final financing requires professional review.